
Who's Really on the Other End of That Medicare Call? The phone rings. The voice on the other end says your name, your age, and your address. It sounds official. It may even sound friendly. And within a minute, you are being asked to confirm your Medicare number. What do you do? Complaints about Medicare-related scam calls have climbed sharply over the past year. Reports to the Better Business Bureau indicate that these kinds of calls remain a major concern for people Medicare. Some have even described getting dozens of these calls in a single day. Enrollment season tends to make it worse, because legitimate outreach picks up at the same time criminals do. Here is how these calls tend to sound, and how to protect yourself. The Three Pitches You Are Most Likely to Hear Many Medicare scam calls follow similar scripts. Once you recognize a few key patterns, the calls lose a lot of their power. "You qualify for extra benefits" A recorded voice says it is reaching out to make sure you receive unclaimed Medicare benefits. The recording asks whether you have Part A and Part B, then transfers you to a live person. The real goal is either to get your personal information or to switch you to a plan you did not ask for. "Your card is expiring" The caller warns that your Medicare card is about to expire, or that your coverage could be interrupted unless you verify a few details. Fear and urgency are the strategy here. If you hand over your Medicare number or Social Security number, criminals can use it to steal your identity or bill you for services you never received. "Something free is on the way" Free braces. Free hearing aids. Free gift cards or a free smartphone. The offered gift is bait. One woman in Texas received a large box of orthopedic braces she never ordered, and later learned Medicare had been billed more than $700 for them. Her secondary insurer was charged as well, and additional claims were filed for supplies she never requested. Fraudulent claims can also leave inaccurate information in your medical records, including diagnoses for conditions you do not have. Fake Agents Are Part of the Problem Not every scammer sounds like a robot. Some present themselves as licensed insurance agents. They may reference a well-known carrier, quote a plan name, or offer to walk you through your options right now over the phone. A few things a real agent will not do: • Pressure you to decide something during a first call • Refuse to give you a full name, license number, or office phone number • Ask you to pay by gift card, wire transfer, or a payment app • Tell you that you must act today or lose your coverage • Show up at your door uninvited to sell you a plan Verifying an agent is simpler than most people expect. Ask for their name and license number, then hang up and call the agency's main office number yourself. You can also check the license with your state Department of Insurance. Anyone who is legitimate will not mind you doing this; they know you need to be careful. Habits That Keep You Safe • Treat unexpected Medicare calls with skepticism, even friendly ones • Never give your Medicare number, Social Security number, or bank details to someone who called you • Remember that Medicare generally reaches out by mail first and does not call to ask for your Medicare number or banking information • Hang up on anyone who pressures you or claims your coverage is at risk • Read your Medicare Summary Notices and Explanation of Benefits statements and look for charges you do not recognize • Report anything unfamiliar right away Hanging up may feel rude, but it is the single most effective thing you can do. If You Think You Already Shared Something You Shouldn't Have Act quickly, but do not panic. Write down what you shared and when. Review your recent statements. Then report it. You can contact the Senior Medicare Patrol program in your state, call 1-800-MEDICARE, or file a report with the Federal Trade Commission at ReportFraud.ftc.gov. The Easiest Defense Is a Person You Already Know Scam calls work because they catch people on their own and unsure. Having a licensed agent you already trust means you have someone in your corner. You have a number you can call to ask whether an offer is real before you respond to it. If you have questions about a call you received, or you want a second set of eyes on your current coverage, reach out to our office. We are here to help you!
Annual Enrollment for Medicare runs October 15 – December 7, 2026. Here's what to know about comparing plans, key dates, and how to get ready.
September is Suicide Prevention Month. Learn what to watch for, how to start a hard conversation, and where to turn for help. Support matters more than perfect wording.
How Medicare Enrollment Can Create Consequences for Your HSA Contributions Many Americans spend years building savings in a Health Savings Account (HSA), one of the most tax-advantaged ways to save for health care expenses. HSA funds can be used for many qualified medical expenses, including deductibles, copays, coinsurance, prescription medications and certain medical equipment… even when you are on Medicare. That is why HSAs can be such an important part of your retirement planning. But when Medicare enters the picture, the rules can lead to unexpected tax consequences. Where Medicare Can Create a Problem with HSAs Some people continue working after age 65 and remain covered by an employer-sponsored HSA-eligible high-deductible health plan (HDHP). That's allowed. Simply turning 65 or becoming eligible for Medicare doesn't automatically prevent you from contributing to an HSA. The issue begins when you are actually enrolled in Medicare. Once you're enrolled in Medicare Part A and/or B, you generally can no longer contribute to an HSA. The confusion is that Medicare enrollment doesn't always happen when people expect it to. One way this can happen is through Social Security benefits. If you're already receiving Social Security benefits when you become eligible for Medicare, you're generally automatically enrolled in Medicare Part A and Part B. While Part B can generally be declined, premium-free Part A usually takes effect automatically. Once Part A coverage begins, you're no longer eligible to contribute to an HSA, even if you're still working and covered by your employer's HSA-eligible health plan. That means someone could continue making HSA contributions through payroll, or continue receiving employer contributions, without realizing that Medicare coverage has kicked in and made them ineligible to make those contributions. A second issue can arise when someone delays Medicare while continuing to work and contribute to an HSA. When that person later applies for premium-free Medicare Part A after age 65, their Part A coverage can generally be retroactive for up to six months, but not earlier than the month they first became eligible for Medicare. This creates a potential HSA problem because a person can't make HSA contributions for months in which they're covered by Medicare. If Part A is applied retroactively, HSA contributions made for those retroactively covered months may become excess contributions, even though the person wasn't aware at the time that Medicare coverage would later reach back to those months. For example, someone who works past 65, keeps an HSA-eligible employer plan and delays Medicare might continue contributing to an HSA. If they later enroll in Medicare and receive six months of retroactive Part A coverage, some of those recent HSA contributions may no longer be allowable. That's why it's important for people who work past 65 to coordinate the timing of Medicare enrollment, Social Security benefits, and HSA contributions. The Potential Tax Consequences The IRS generally imposes a 6% excise tax on these “excess” HSA contributions that aren't corrected as permitted under IRS rules. The tax can apply for each tax year the excess remains in the account. In some cases, an individual may be able to avoid the 6% excise tax by withdrawing the excess contribution, along with any earnings attributable to it, by the applicable tax-return deadline and properly reporting the correction. Because the tax treatment depends on the circumstances and timing, anyone who discovers a possible excess contribution should consider contacting the HSA custodian and a qualified tax professional. How to Avoid HSA Contribution Problems If you're approaching Medicare eligibility, planning to enroll in Medicare, or applying for Social Security benefits after age 65, review your HSA contribution strategy ahead of time. The correct time to stop contributing isn't the same for everyone. For example, if you enroll in Medicare during your Initial Enrollment Period, you generally need to make your last HSA contribution for the month before your Medicare Part A coverage begins. Special rules can apply if your birthday is on the first day of a month. If you delay Medicare and later enroll in premium-free Part A, Medicare recommends accounting for the possibility that Part A coverage will be retroactive. If you enroll six or more months after turning 65, that generally means stopping HSA contributions six months before the month you apply for Medicare or Social Security benefits. Because enrollment dates and individual circumstances can vary, confirm the effective date of your Medicare coverage before determining your final HSA contribution. Your HSA Can Still Be Valuable After Medicare Enrolling in Medicare means you can no longer make HSA contributions, but it doesn't mean you can't use the money already in your account. You can continue pulling from your HSA after enrolling in Medicare, and withdrawals for qualified medical expenses can generally remain tax-free. HSA funds can therefore continue to be a valuable resource for health care expenses throughout retirement. The key is planning ahead. Understanding when Medicare coverage begins, and when HSA contributions must stop, can help you preserve the tax advantages you've worked to build.
Outdated beneficiaries can send your life insurance money to the wrong person. Learn the common risks and how to keep your policy current.
Learn how to prepare for health care costs in retirement, including Medicare, retiring before 65, long-term care, HSAs, and supplemental insurance options.
Every fall, Medicare Advantage and Part D plans mail an Annual Notice of Change. Learn what it means for your costs, coverage, and doctors next year.
GLP-1 medications help you eat less — but eating less can mean fewer nutrients. Here's what the latest research shows and how to eat well.
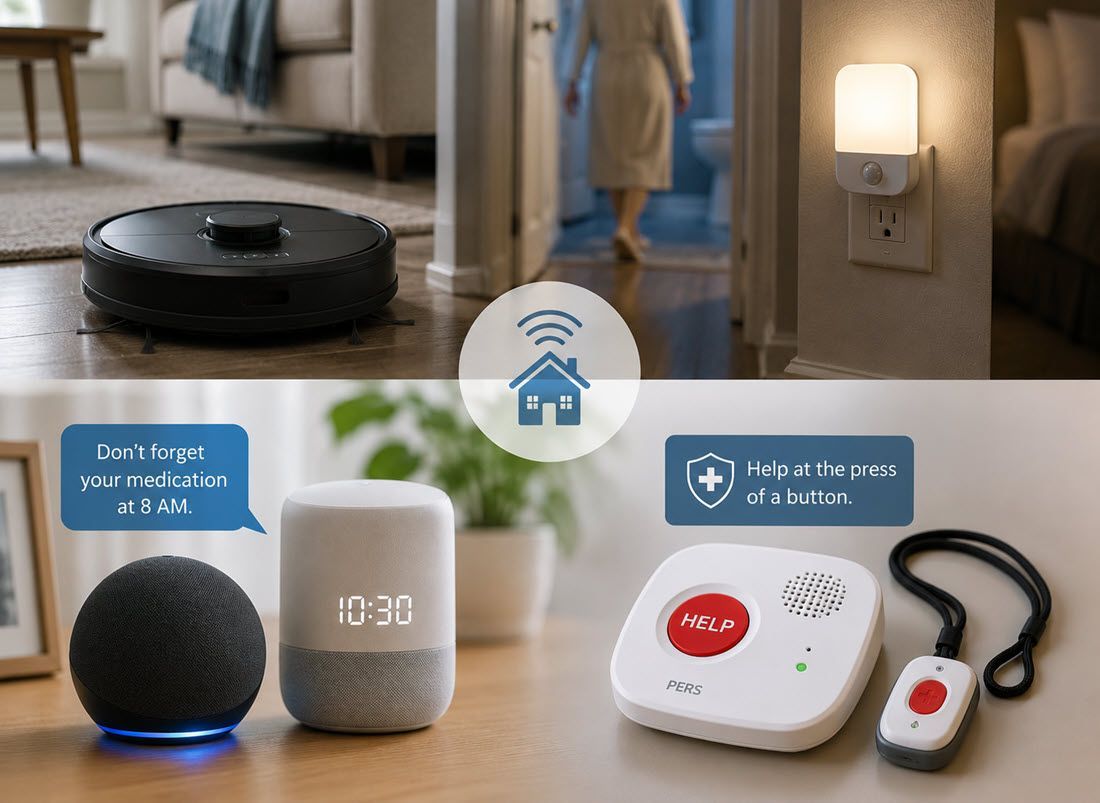
See how smart lighting, robot vacuums, stove shut-offs, medication reminders, and fall monitors can help seniors at home, plus what Medicare and Medigap do and do not cover.
U.S. News & World Report has rated over 12,000 home health agencies. Learn how the rankings work and why they matter for your care and coverage decisions.